

As students begin fall classes at America’s colleges and universities, the classroom lecture they will not receive, but which will impact them directly, is on how universities arbitrage federal tax subsidies.
Over the years, schools have amassed large endowments that generate billions in investment income. But only a portion of these earnings go to support students and operations, and even less is used for improving or expanding facilities. Instead, universities often finance these projects with tax-exempt bonds at interest rates far less than the market rate and, typically, at half the rate of return they can earn on their investments. Arbitraging their borrowing costs and investment income allows universities to continue growing their endowments at taxpayer expense but with no impact on classroom outcomes.
Here is how indirect arbitrage works.
University endowments are funded through tax-deductible donations by alumni and patrons. These funds are then invested to generate income that is also largely tax-exempt.[1] Based on my analysis of data provided in the 2025 NACUBO-Commonfund Study of Endowments, the endowments of US universities have nearly doubled in size over the past decade, growing from $536 billion in 2015 to $941 billion in 2025. The average endowment is now worth $1.4 billion.
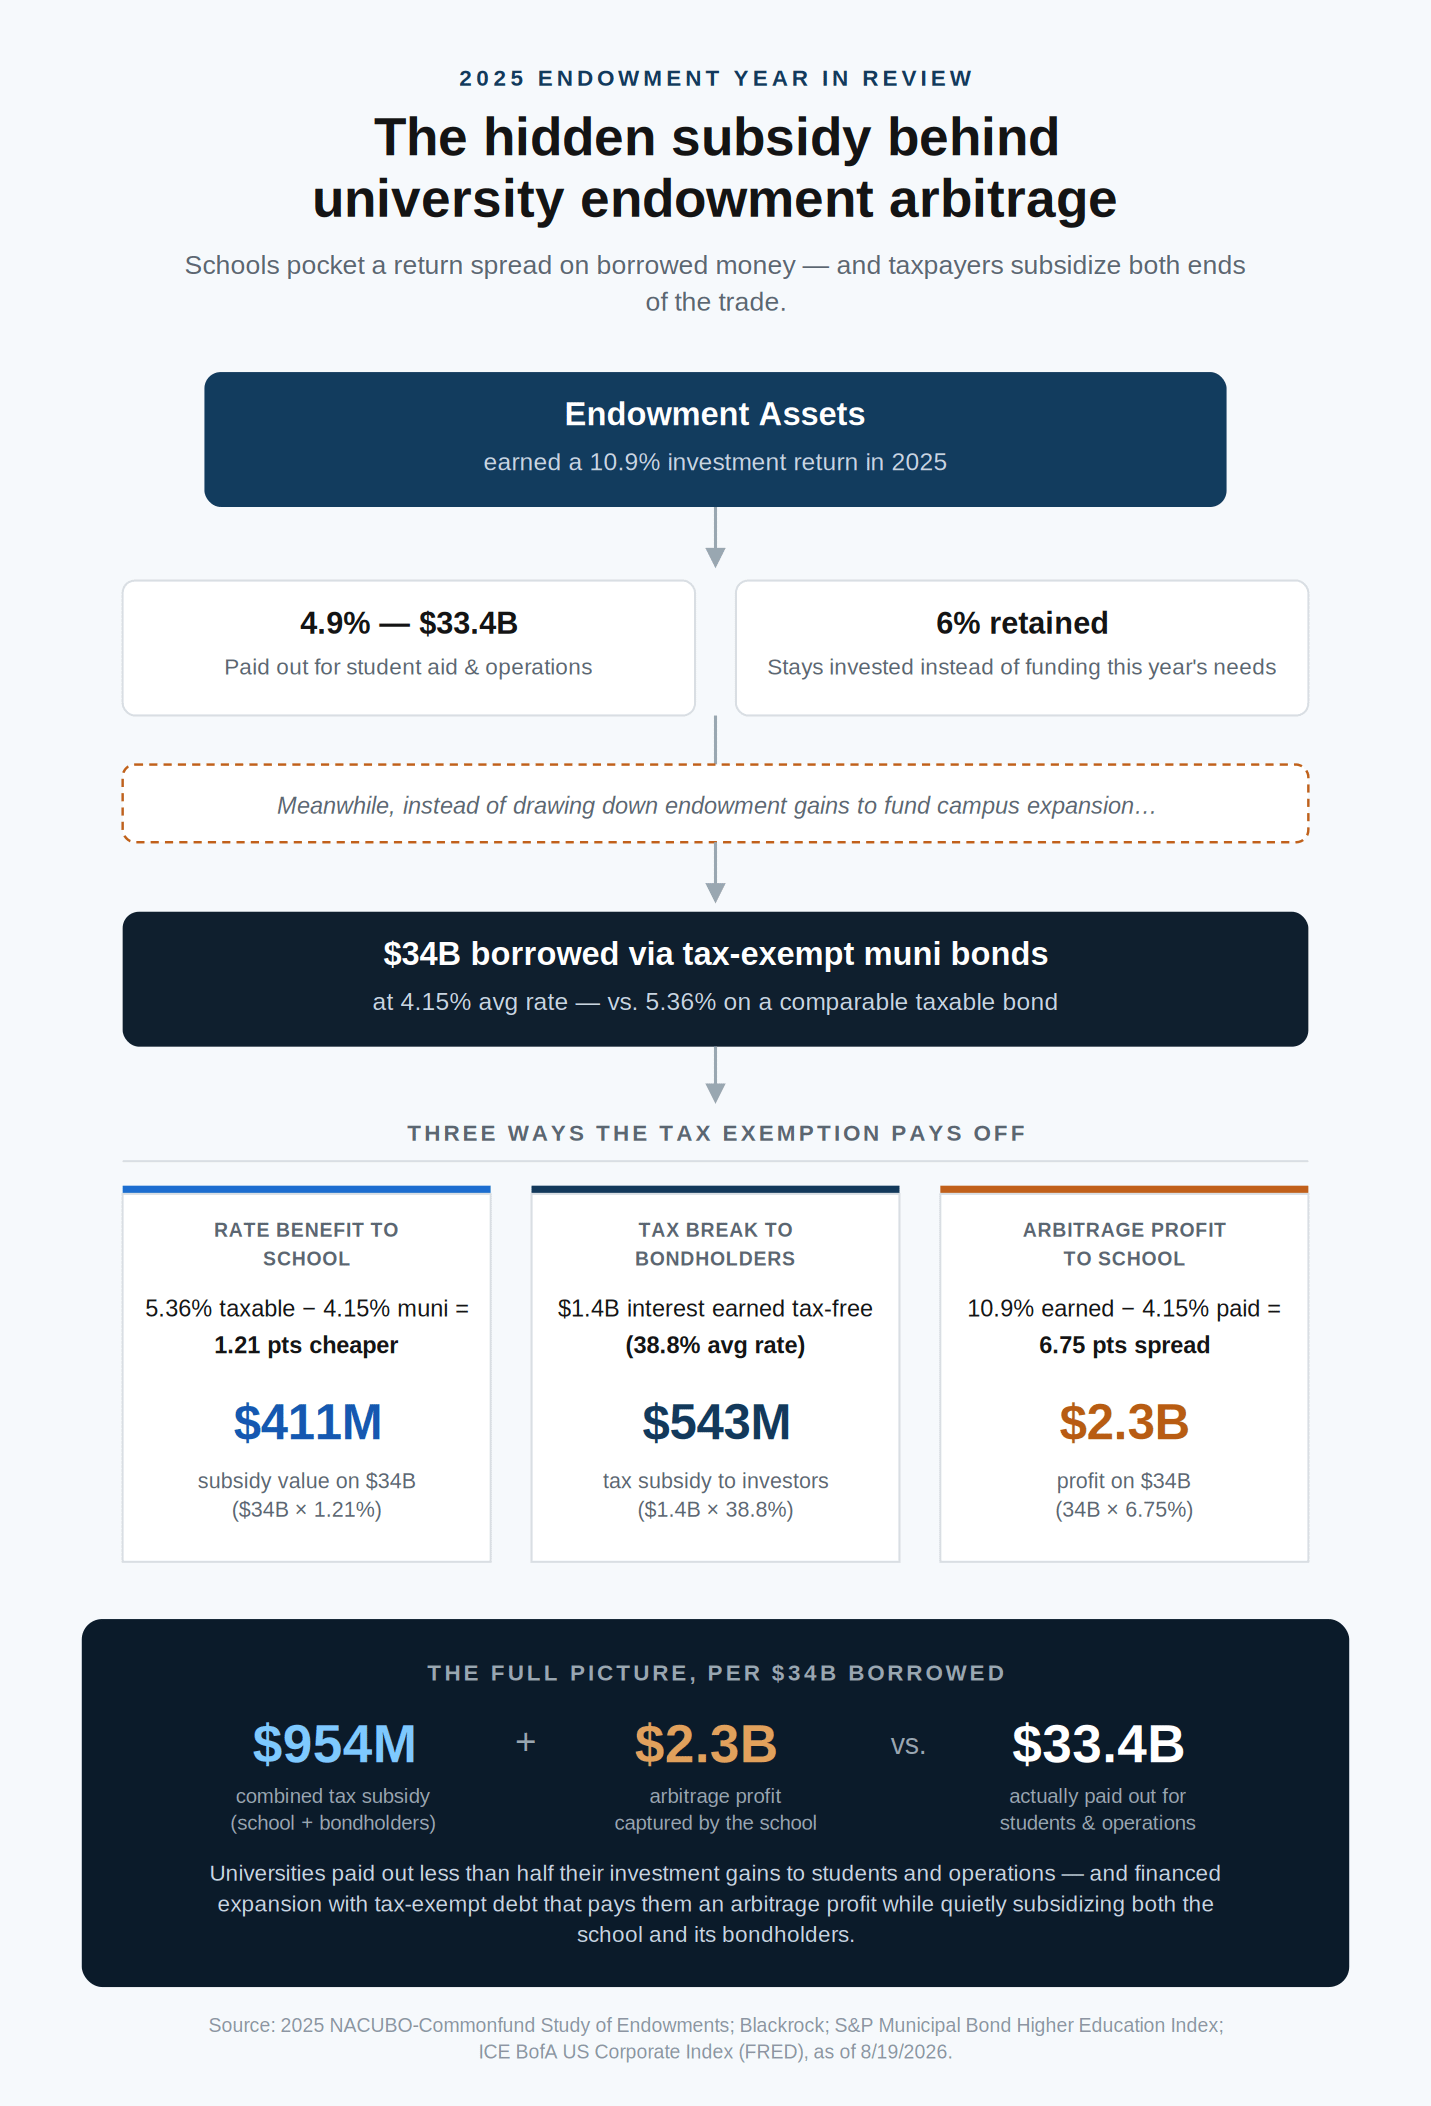
Universities have done well with their investments. According to the NACUBO-Commonfund study, universities reported investment returns of 10.9% last year. But not all of those earnings were plowed back into operations or student aid. As the graphic below illustrates, universities spent 4.9% of their assets on a combination of financial aid, operations, faculty positions, and academic programs. That amounted to $33.4 billion in 2025.
In short, universities earned investment returns of 10.9% but paid out only 4.9% of their assets toward student aid and operations. This leaves 6% to be retained for continued investing. This is how endowments have continued to grow over the past few decades.
The second way that universities protect their endowments and still finance large capital projects such as stadiums, dorms, and classrooms, is to fund projects with tax-exempt municipal bonds. These are known as private activity bonds.
In 2025, Blackrock reports that US colleges and universities issued more than $34 billion in tax-exempt muni bonds, a 28% increase from the prior year. Perhaps only coincidentally, the amount they borrowed through muni bonds is roughly equivalent to how much of their assets they spent on operations and student aid.
The interest rate on municipal bonds is lower than on traditional bonds because investors don’t pay income tax on their earnings. According to the S&P Municipal Bond Higher Education Index the yield on higher education bonds is 4.15% (as of July 2026), compared to a rate of 5.36% on taxable corporate bonds, per the ICE BofA US Corporate Index (as of August 19, 2026). Although the difference in the rates is only 1.21 percentage points, this saves universities $411 million in interest payments on $34 billion in borrowings. Those savings are subsidized by taxpayers.
There is another way universities profit from these transactions, known as the arbitrage profit. Universities profit by generating a larger return on their investments than the interest rate they pay on the muni bonds. In 2025, there was a 6.75 percentage point difference between the returns universities generated on their investments (10.9%) and the interest rate they paid on their bonds (4.15%). On $34 billion worth of bonds the arbitrage profit amounts to $2.3 billion. Again, this is largely subsidized by taxpayers.
Investors are subsidized too
There is yet another party that benefits from taxpayer subsidies in these transactions—investors. Remember, investors don’t pay taxes on the interest income they earn on the bonds they’ve purchased. The value of the tax subsidy is larger for taxpayers in higher tax brackets and bondholders tend to be high-income individuals. To illustrate this, let’s assume they have a tax rate of 38.8%.[2] As the graphic below shows, at a tax rate of 38.8% investors would save $543 million in taxes on the interest income from $34 billion in bonds. Again, these savings are subsidized by taxpayers.
Cheap bonds can fund climbing walls but do not improve classroom performance
A study by economists Matteo Binfarè and Kyle E. Zimmerschied, found that all of this taxpayer subsidized borrowing has not lead to better outcomes in the classroom but has likely contributed to the rising cost of higher education. The economists determined that universities are not taking on debt to expand facilities in response to growing student enrollment, but instead to improve “dormitories, parking garages, athletic facilities, or student centers.” They determined that “universities have increasingly used debt as a tool to cater to student demand for increasing amenity quality, with no evidence of spillovers to education quality.”
Binfarè and Zimmerschied estimated that in 2020 “the average university paid approximately $1,000 per student in interest expenses.” That figure is likely much higher today.
Arbitrage is prohibited but money is fungible
At this point you may be thinking, “aren’t there rules against these transaction?” Yes, the rules governing muni bonds do prohibit outright arbitrage—using cheap borrowed money to invest—but money is fungible. As long as universities can access the cheap money of muni bonds, they will continue to avoid dipping into their endowments to fund expansion projects. Every dollar they can borrow through muni bonds is a dollar they don’t have to spend from their endowments—which can earn investment returns of 10% or more annually.
Universities may be the most tax-exempt or tax-subsidized sectors in the US economy. Their only rival are nonprofit hospitals. They take advantage of their tax-exemption to arbitrage tax-free municipal bonds at the expense of students and taxpayers alike, which allows them to continue earning big tax-free returns on their investments. Repealing the ability of universities to tap muni bonds would be a good first step toward making them responsible for spending their own money.
[1] The OBBBA modified a tax on the net investment returns of some large endowments that was enacted in the 2017 Tax Cuts and Jobs Act. The original JCTA tax affected only 45 endowments in 2024 and raised $168 million. OBBBA’s modifications dramatically reduced the number of endowments impacted. The Joint Committee on Taxation estimated that it would raise just $80 million in 2026.
[2] The top income tax rates are 32%, 35%, and 37%. Investment income is also subject to the 3.8% Net Investment Income Tax (NIIT). For this example, we are assuming a taxpayer in the 35% bracket, who then pays the 3.8% NIIT for a combined rate of 38.8%.