

I’d like to share with you the introduction to a new study I just posted on the academic platform SSRN. (You can find it here). The paper challenges the conventional “relatedness” standard that allows nonprofits to engage in all manner of business activities, tax-free. I propose a new “commerciality standard” that protects charitable donations while taxing the business income of nonprofits.
Introduction
“Eventually all the noodles produced in this country will be produced by corporations held or created by universities…”
Representative John Dingell of Michigan during the debate over UBIT (1950)[1]
The failures of the past inevitably catch up with the future. In 1950, the tax-exempt sector was out of control. Not only were university owned businesses encroaching on the turf of taxpaying for-profit firms, but they were becoming a political embarrassment. The poster child for nonprofit abuse of the system—and the target of Rep. John Dingell’s complaint—was New York University and its ownership of the Mueller Company, a leading manufacturer of macaroni.
Pasta making was only part of NYU’s business empire. It also owned other companies that could claim tax-exempt status, including one that made piston rings, another that made fine China, and one that processed leather. NYU was not alone. Columbia University owned much of the land under Rockefeller Plaza in New York City and Cooper Union College owned the property under the Chrysler Building. Other universities owned department stores, hat makers, citrus groves, movies, and cattle ranches.[2] And the profits generated by these commercial enterprises accrued to the universities tax-free.
The incongruity of institutions of higher learning owning factories and cattle ranches had reached a breaking point because nonprofit law operated under the “destination-of-income” test. It held that “An organization could engage in unlimited amounts of commercial activity as long as the revenues from that activity were used for charitable purposes.”[3] Although the destination-of-income test developed organically from a series of court decisions during the 1920s[4], it largely stemmed from the failure of lawmakers at the turn of the 20th Century to establish principled guardrails when they exempted certain commercial activities from the first corporate income tax.
Dingell and his colleagues tried to address the headline-grabbing excesses of tax-exempt businesses by creating the unrelated business income tax (UBIT) as a provision within the Revenue Act of 1950. UBIT replaced the destination-of-income test with a “relatedness” test. This test says that nonprofits can engage in commercial activities so long as it is related to their core mission. Commercial activities that are unrelated to the core mission will be taxed at the statutory corporate tax rate.
But as we will see, the relatedness test failed to put clear guardrails on the nonprofit sector. If Rep. Dingell were alive today, he would be lamenting a tax-exempt sector that has grown into a $3.6 trillion economy commanding nearly 13 percent of GDP. Most nonprofit revenues today are not from charitable donations. On the contrary, roughly 80 percent of nonprofit revenue is derived from business-related or commercial sources such as insurance payments, ticket sales, TV broadcast rights, royalties, licensing fees, memberships, payments from Medicaid and Medicare, government contracts, tuition, rents, advertising, sponsorships, and investment returns. The income derived from this commercial activity enjoys a taxpayer subsidy by being tax-exempt.
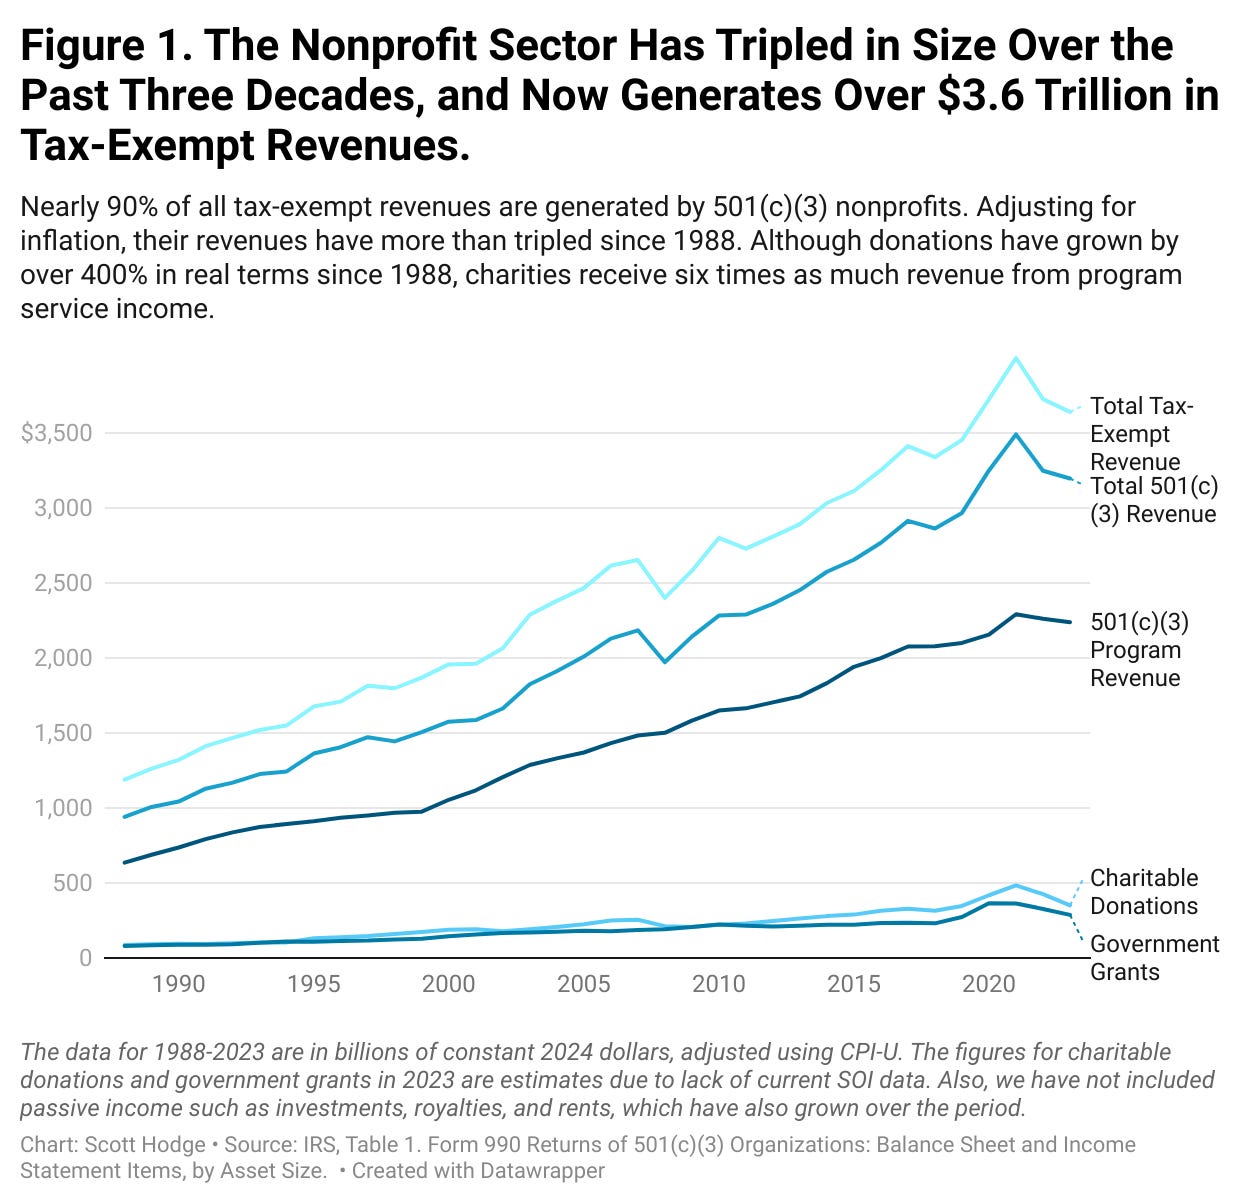
The relatedness test is so malleable that it fails to prevent nonprofits from competing with for-profit companies and, in some cases, has allowed nonprofits to dominate some industries. For example, more than half of all hospitals in the U.S. are nonprofits. Cash-rich credit unions are buying community banks. And large nonprofits run nation-wide dental networks, insurance companies, and investment firms. The growth of these large nonprofit businesses has greatly narrowed the corporate tax base and threatens our free enterprise system by pitting tax-paying businesses against tax-exempt ones.
Moreover, “relatedness” has been a challenging concept for taxpayers to comply with, for courts to interpret, and for the IRS to administer. It has opened the door to rent seeking and political manipulation. For these reasons, the relatedness standard needs to be replaced with an objective standard that clearly distinguishes between real charitable activities and commercial activities.
This paper proposes to replace the “relatedness” test with a commerciality test designed to protect the donative income of charities while taxing their business-related income. The paper explores three methods of separating donative income from commercial income. The first method is the “donative theory” of nonprofits developed by professors Mark A. Hall and John D. Colombo, which seeks to define a charity based on the amount of private donations it receives. The second is the “collectiveness (or publicness) index,” created by Professor Burton Weisbrod. It says that the greater the share of donative income a nonprofit receives the more charitable it looks, whereas the smaller the share it receives the more it looks like a private business. The next method is the commerciality test proposed by professors James T. Bennett and Gabriel Rudney which uses a 10-part test to define the business or commercial activity of nonprofits.
The UBIT replacement proposal presented here borrows from each method. This proposal walls off charitable gifts, grants, and contributions from private donors, and then assumes that all other sources of income—such as program service, investment, royalty, and rental income—are by definition “commercial” in nature and, thus, taxable. I then use the 990 nonprofit tax return to guide the process of separating donative income from taxable commercial income.
This proposal is rules based, easier to administer, and removes the taxpayer subsidy of nonprofit commercial activity that has existed for nearly 120 years. And it has the potential to raise upwards of $51 billion annually in tax revenues that can be used to address the nation’s debt crisis or finance pro-growth tax reforms.
[1] U.S. Congress, House Committee on Ways and Means, Hearings on Revenue Revision of 1950, 81st Cong., 2nd sess., 1950, 580. https://catalog.hathitrust.org/Record/100717075.
[2] Adolph J. Sabath, statement in Congressional Record—House, vol. 96, pt. 7 (June 27, 1950), 9274. https://www.congress.gov/bound-congressional-record/1950/06/27/house-section.
[3] John D. Colombo, “Reforming Internal Revenue Code Provisions on Commercial Activity by Charities,” Fordham Law Review 76 (2007): 667–691. https://fordhamlawreview.org/wp-content/uploads/assets/pdfs/Vol_76/Columbo_Vol_76_Nov.pdf.
[4] James J. Fishman, Stephen Schwarz, and Lloyd Hitoshi Mayer, Taxation of Nonprofit Organizations, 6th ed. (St. Paul, MN: Foundation Press, 2021), 599.